September 2026 · Tenants
FedEx is repricing industrial quality, not credit
FedEx is redefining what logistics real estate it wants to own for the next decade.
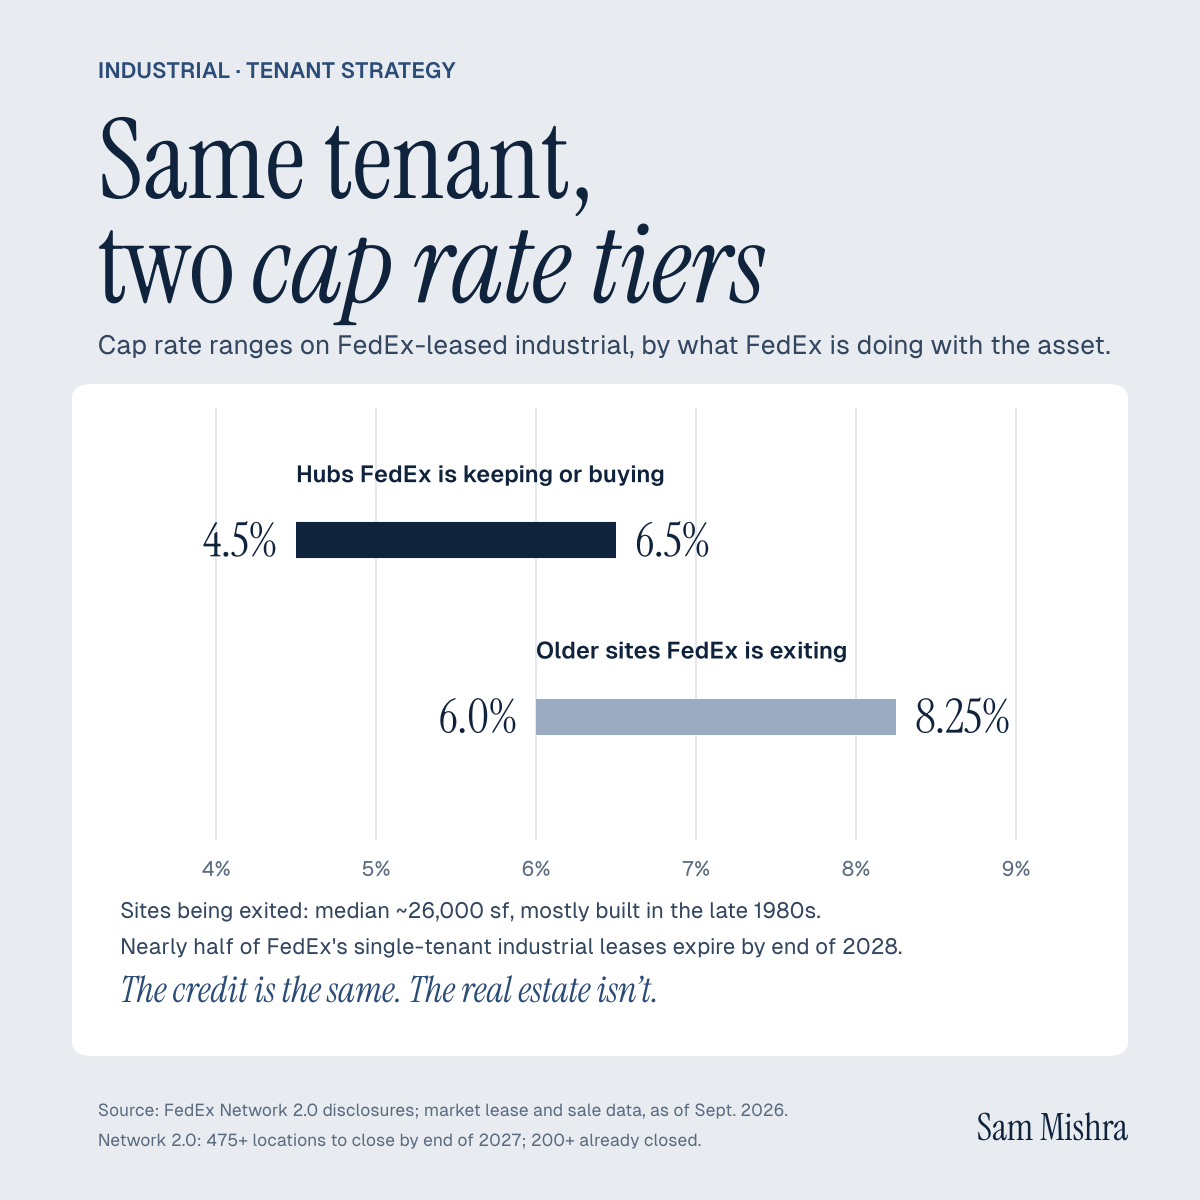
FedEx Network 2.0 will close more than 475 locations by the end of 2027, with more than 200 already shuttered. Once you dig into the lease data, the strategy becomes much more apparent.
This goes well beyond broad cost-cutting. It reflects a migration toward larger, more modern facilities that better support today’s logistics network.
A few observations:
- The buildings being exited have a median size of roughly 26,000 square feet and were largely built in the late 1980s.
- Nearly half of the 68 single-tenant FedEx industrial properties in DealGround’s lease data — 33 of them — have leases expiring by the end of 2028.
- Cap rates on these shorter-duration assets range from 6.0% to 8.25%, compared with 4.5% to 6.5% for the larger hubs FedEx is retaining or purchasing.
- The ownership profile is just as telling. The long-term hubs are largely held by institutional owners, while many of the locations being vacated are owned by individuals, family partnerships or single-purpose LLCs.
I think that’s the broader story. This is a repricing of industrial quality rather than tenant credit. FedEx’s credit profile remains strong, but the company is becoming far more selective about the physical assets it wants in its network.
For investors, that changes the underwriting conversation. Lease expiration dates are still important, but so is building functionality, location and long-term relevance within a tenant’s operating strategy.