September 2026 · Capital formation
They bought the origination, not the assets.
Institutional capital has arrived in net lease industrial, and the numbers aren’t small.
In September, J.P. Morgan Asset Management closed its second net lease fund at $1.1B against an initial $500M target — 2.2 times the raise it set out for. The mandate is specific: supply-chain-critical industrial and industrial outdoor storage, underwritten to onshoring. Three more platform deals sit alongside it:
- Goldman Sachs agreed to acquire LCN Capital Partners — about $3B under supervision, sale-leaseback and build-to-suit across North America and Europe — for up to $410M, roughly 80% of it payable in equity.
- CBRE Investment Management bought Tenet Equity from Cerberus for $1.6B: more than 200 properties, about 12M square feet, 39 states.
- BlackRock completed its acquisition of ElmTree Funds, a $7.3B net lease manager, and folded it in alongside HPS.
Read those as capital raises and you miss what actually happened.
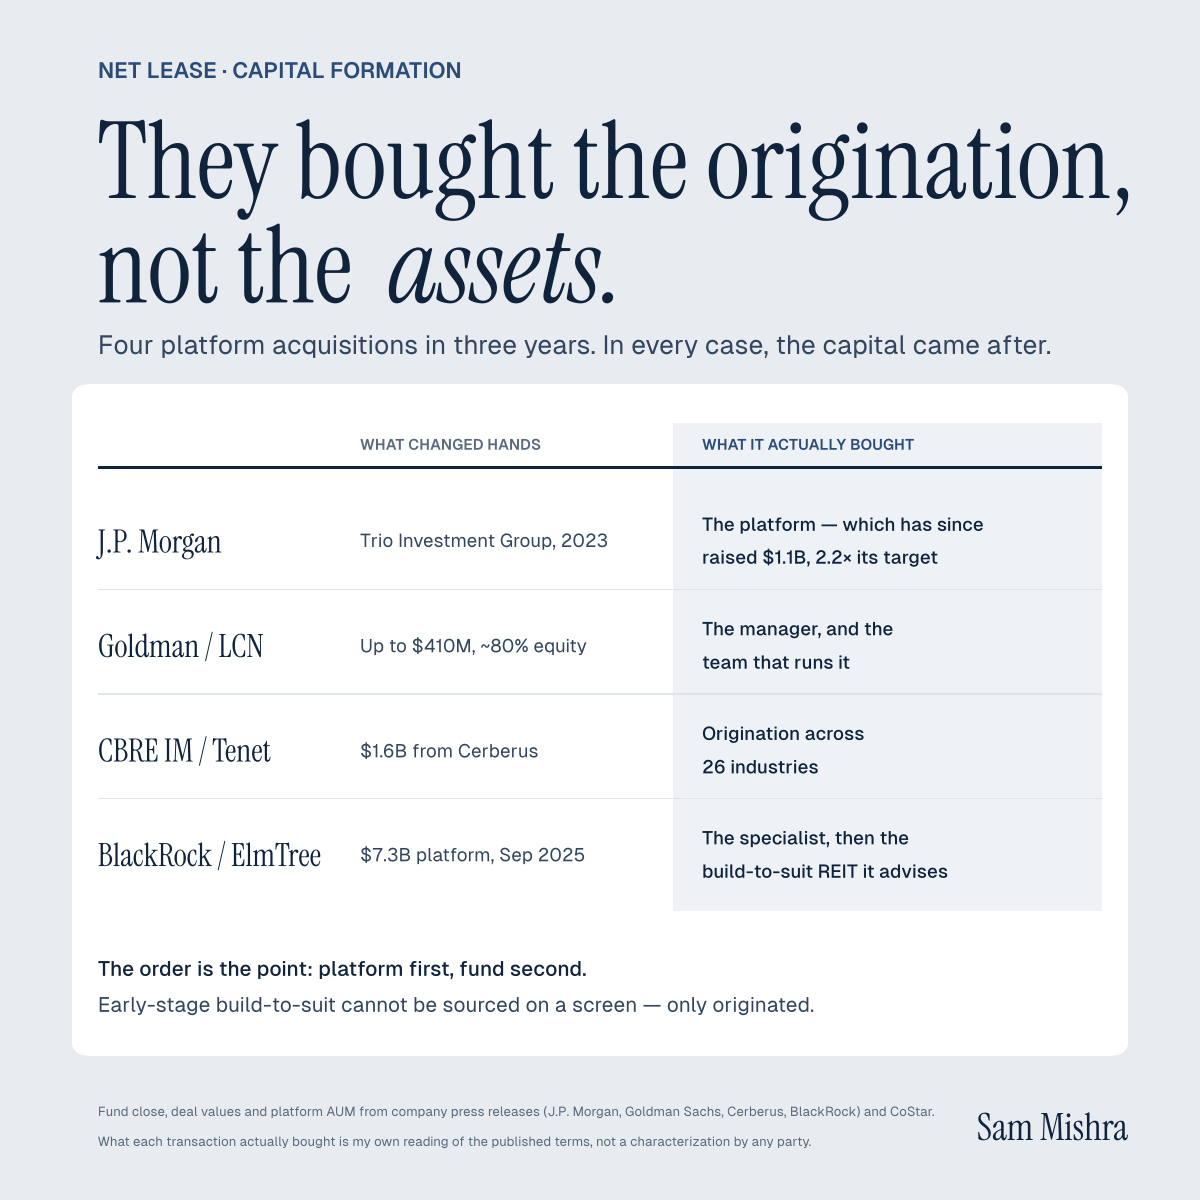
Only the J.P. Morgan fund was a raise — and J.P. Morgan bought Trio Investment Group, the platform that fund sits on, three years before raising it. The other three bought managers. Goldman paid around 80% in equity, which is how you buy a team rather than a book of assets. CBRE IM bought a platform built from nothing since 2021. BlackRock bought a specialist.
The reason shows up in what they say they’ll do with it. BlackRock’s HPS Net Lease Income REIT, formed in December 2025 with ElmTree as its external adviser, is pointed primarily at early-stage build-to-suit — development-stage investments and newly constructed buildings. You cannot buy that on a screen. It takes years of standing relationships with corporate occupiers and the developers who serve them.
The capital arrived faster than the capability. So they bought the capability.
One caveat on my own argument: Tenet isn’t an industrial platform. It’s middle-market net lease across 26 industries and more than 65 tenants. It’s evidence of net lease consolidation, not industrial consolidation specifically. The industrial-specific bets here are the J.P. Morgan fund and the HPS REIT.
Behind all of it is an allocation shift. Larry Fink’s 2025 letter put a number on it — “the future standard portfolio may look more like 50/30/20” — moving a fifth of the standard portfolio into private assets. Net lease is one of the few real estate strategies that can absorb money at that scale without becoming something else: long leases, credit tenants, cash flow you can model.
Capital was never the scarce input.
What these three years repriced is the ability to find the deal before it exists.