October 2026 · DST
DST demand is running ahead of supply
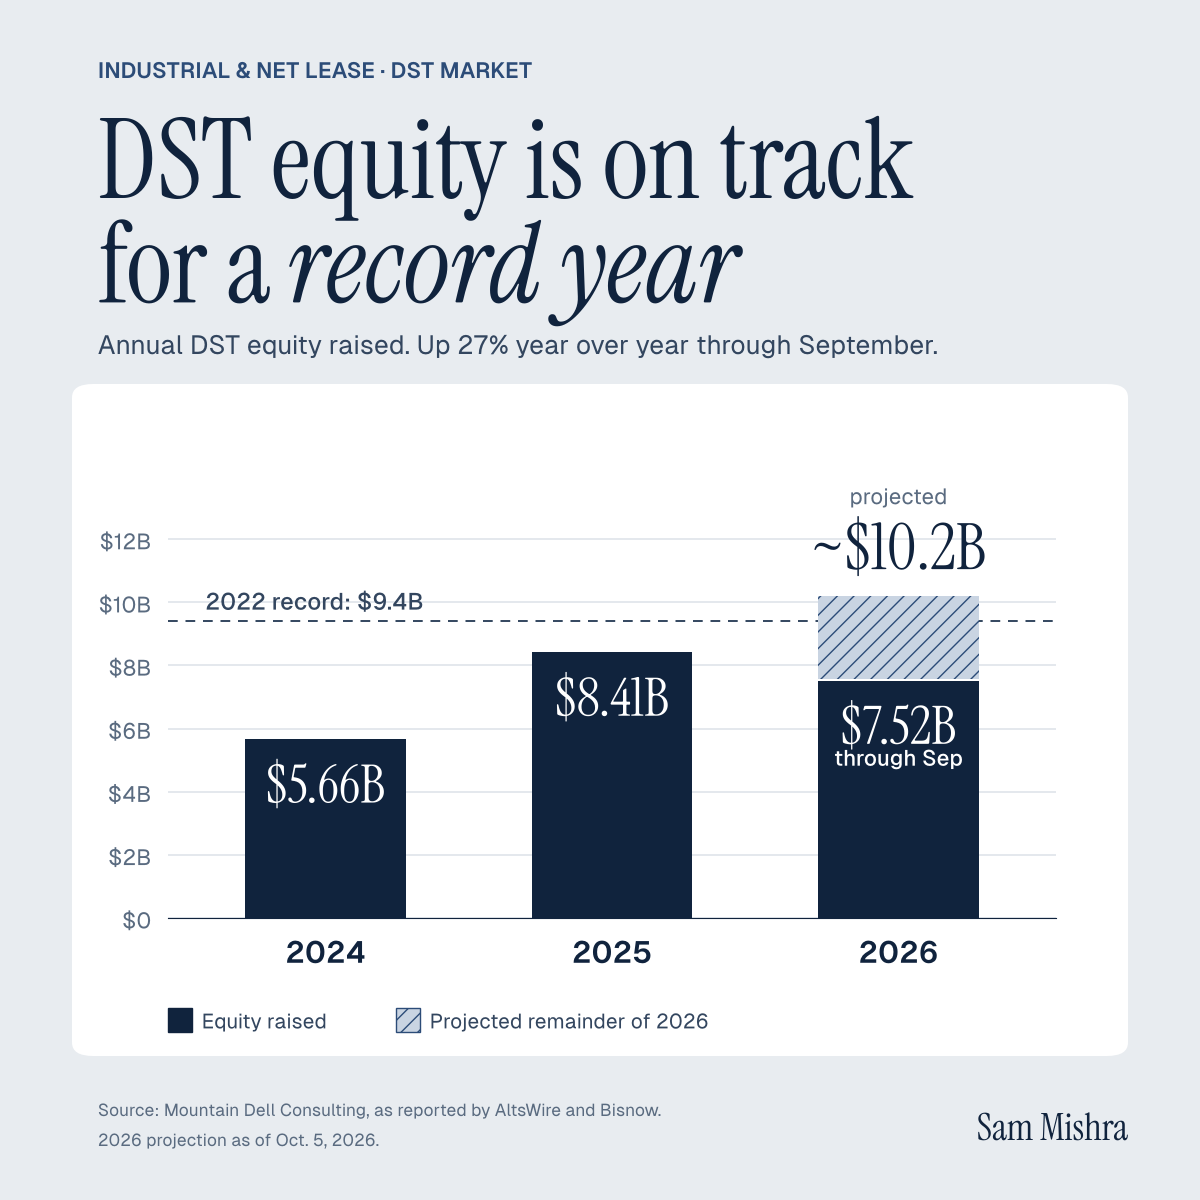
I’ve written that DST capital is deepening demand for credit-backed net lease. The September numbers suggest that demand is now running ahead of the supply of quality product.
DST equity raised hit roughly $7.5B through September, up 27%, and Mountain Dell now expects about $10.2B for the year.
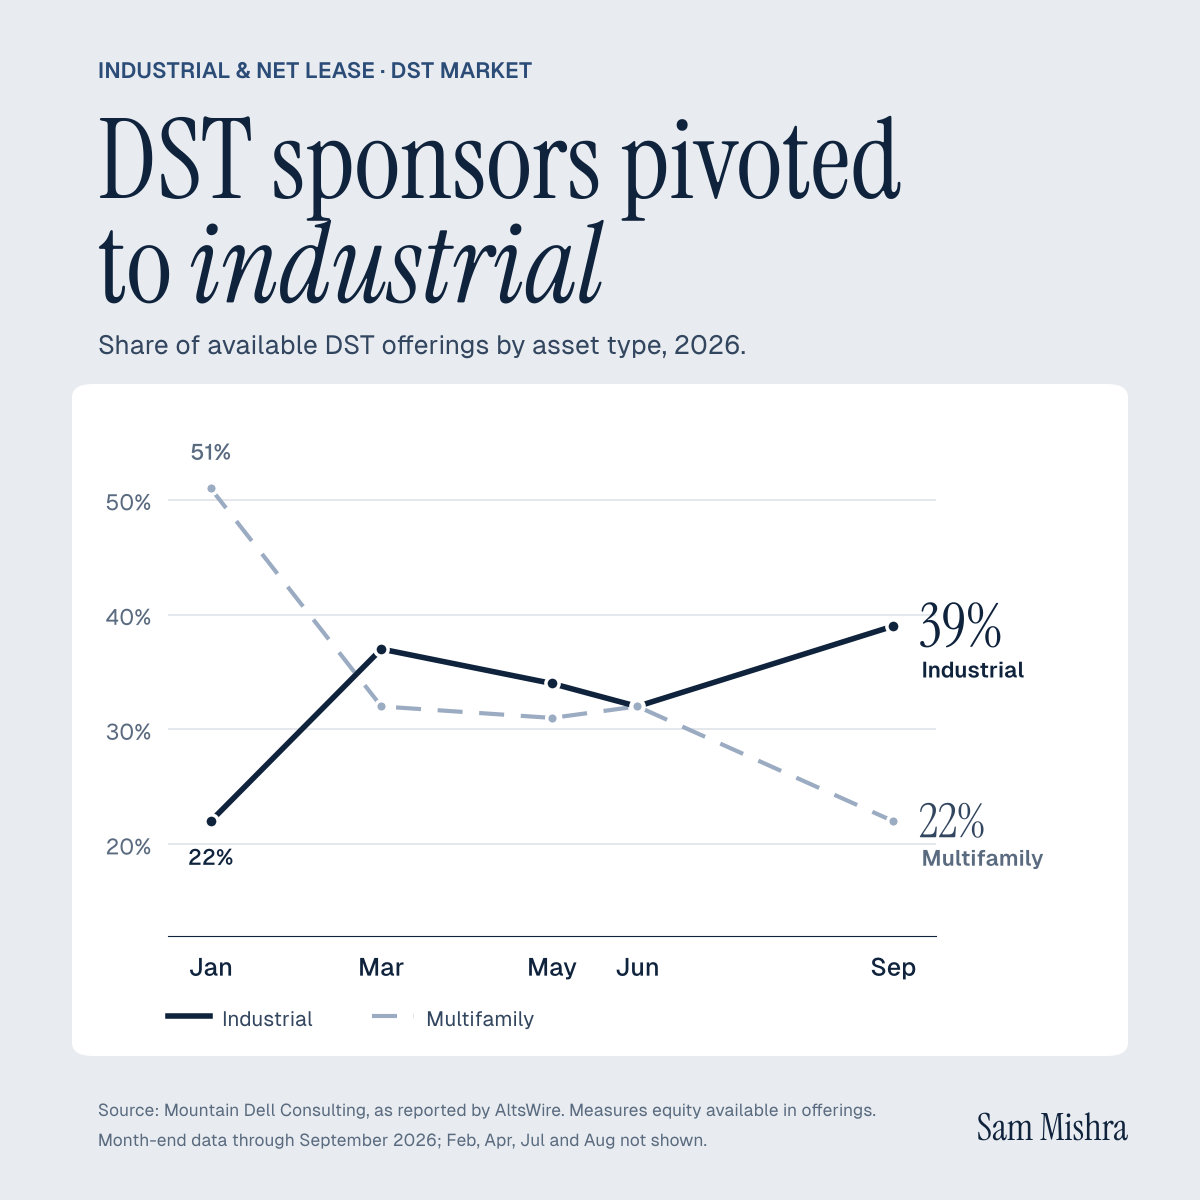
Average days on market fell from about 309 to 203. Industrial has gone from roughly a fifth of available offerings in January to 39% today. September’s largest launch was a $538M industrial program. More sponsors are raising faster and deploying into the same pool of credit-tenant industrial, which means pipelines empty sooner and competition for each well-located asset gets tighter.
At the same time, the 10-year crossed 5% and the Fed hiked in September. Investors now weigh a DST distribution against a risk-free yield that hasn’t been this attractive in nearly two decades. That leaves less room to pay up for product.
The league table is moving too. Blue Owl climbed to No. 2, ExchangeRight to No. 3, and JLL Exchange broke into the top five. Raising equity at scale is increasingly table stakes. The differentiator looks more and more like who can consistently source assets that still pencil at the yield investors expect.
That’s where off-market origination earns its keep: long-standing relationships with developers delivering new product, and with net lease owners ready to exit, often before a deal ever reaches a broker’s list.
For sponsors: is your bigger constraint today raising equity or finding product that meets your target distribution?